
Is Tilray a Buy at Its Record Low, or Is It a Value Trap?

 Prefer us on Google


Free ArticleExplore Premium Services
Is Tilray a Buy at Its Record Low, or Is It a Value Trap?
Tilray's recent record revenue wasn't as impressive as it seemed at first glance.
By Prosper Junior Bakiny -- Nov 21, 2026 at 4:51PM EST +Fool.comon
Key Points
Tilray's revenue grew at a good clip in its last quarter, but that was due to an acquisition.
The company's cannabis sales fell 13%, and it swung back to an operating loss.
With U.S. legalization still hard to predict, and regulatory challenges in other countries, a record low alone is no reason to buy.
The cannabis industry has been a massive disappointment in recent years, and even most industry leaders haven't escaped the bloodbath. Take, for instance, Tilray Brands (TLRY -8.70%), one of the largest players in the Canadian cannabis market. Tilray has significantly underperformed the broader market over the past half-decade, losing more than 90% of its value. The company is now near record lows. Is Tilray stock a buy at current levels, or would investors be catching a falling knife?
Image source: Getty Images.
What happened to Tilray Brands?
Tilray Brands faces a difficult regulatory landscape in the cannabis market. Recreational use of the substance remains illegal at the federal level in the U.S. It is legal in Canada, where the company is headquartered, but that market has its own challenges.
Obtaining the proper licenses in Canada is a complex and time-consuming process. The market north of the border is also characterized by stiff competition and persistent supply gluts. Although Tilray is an industry leader, these problems have harmed its financial results. The company has diversified its business in response.
It now operates four segments: cannabis, beverage, wellness (which offers a variety of products, including hemp-based foods), and distribution (which focuses on selling pharmaceutical products in certain international markets). But even a more diversified pool of operations has done little to improve Tilray's financial results.
In the first quarter of its fiscal year 2027, which ended on Aug. 31, Tilray's revenue increased by 23% year over year to a record $257 million. That looks impressive at first glance, but Tilray's top line did not grow that much organically. Earlier this year, it acquired certain assets associated with BrewDog, a craft brewery based in the United Kingdom.
This acquisition added $55.9 million in revenue to the company's total for the period. If we subtract that from Tilray's total revenue, its top line comes in at $201.2 million for the period, down about 4% year over year.
This includes cannabis revenue of $56.1 million, which dropped 13% year over year. Wellness revenue stayed roughly flat at $15.3 million, while distribution revenue was $84.3 million, 14% higher than the year-ago period. Beverage revenue minus the BrewDog acquisition declined 18% year over year to $45.6 million.
So of Tilray's four business segments, only one posted strong year-over-year organic sales growth. Meanwhile, the company's operating loss was $24.1 million, compared with $2.1 million in operating income in the year-ago period. It also turned in a net loss per share of $0.32, after breaking even in the comparable period of the previous fiscal year.
-- Price
What does the future hold?
Tilray's poor financial results aren't the only problem. The company also faces a highly uncertain future, even given recent regulatory progress in the U.S. The federal government reclassified certain medical cannabis products and has discussed broader reclassification, which could encompass recreational cannabis.
But the substance remains illegal at the federal level. That means it still cannot be transported across state lines, among other restrictions. So, Tilray's opportunities in the U.S. remain severely limited. Will that change anytime soon? It's hard to say. Nobody knows if or when the U.S. will legalize recreational use of cannabis at the federal level.
Even if it does, Tilray might face problems similar to those it faced in Canada. What about other countries? Could Tilray bounce back by tapping into international markets? Unfortunately, that also seems unlikely. For instance, Germany legalized recreational cannabis in 2024, but this did very little to boost Tilray's results, despite the company's presence in the country.
Germany allowed people to grow cannabis at home (within certain limits) or join non-commercial cannabis clubs. The law left little room for commercial companies like Tilray. So, the pot grower faces a stringent regulatory environment practically wherever it goes, and that might not change anytime soon. Tilray is unlikely to bounce back.
Investing in the stock, even at its record low, isn't worth the trouble.
| Read Next |
|---|
| Nov 19, 2026 •By Reuben Gregg Brewer Tilray Has More Cash Than Debt and 71% Growth in Europe. Is This Cannabis Stock a Buy? |
| Nov 16, 2026 •By David Jagielski, CPA Why Didn't Tilray Brands Make a Bid for Aurora Cannabis? |
| Nov 15, 2026 •By Keith Speights How to Buy Tilray Stock (TLRY) in 2026 |
| Nov 10, 2026 •By David Jagielski, CPA Does Marijuana Rescheduling Really Help Tilray's Stock? |
| Nov 9, 2026 •By David Jagielski, CPA Tilray Raises Its Guidance for the Year. Is the Stock Finally Headed on the Right Track? |
| Nov 1, 2026 •By Reuben Gregg Brewer Forget U.S. Rescheduling: Tilray's 71% Growth in Europe Is the Story Investors Are Missing |
| ### About the Author |
| Prosper Junior Bakiny is a contributing Motley Fool healthcare analyst covering biotechnology, pharmaceuticals, and healthcare stocks. Before The Motley Fool, Prosper wrote about investing topics ranging from stock market news to private equity for various companies. He holds a master's degree in corporate finance from the University of Maryland Global Campus. |
| TMFPBakiny Prosper Junior Bakiny has no position in any of the stocks mentioned. The Motley Fool recommends Tilray Brands. The Motley Fool has a disclosure policy. |
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like

CrowdStrike's Acquisition of Zscaler Could Become One of the Largest Deals in Cybersecurity Industry

Walsh Wants Fed Officials to Speak Less, but Their Remarks Have Increased

Would Warren Buffett Buy Anthropic? This Is the One Question He'd Have

NVIDIA Stock Price Falls 40% from Highs, Still Hope Remains

Why Bending Spoons May Choose to Issue Convertible Bonds Next

Moderna vs. BioNTech: Why Only 1 Is a Buy Heading Into 2027

JPMorgan Chief Economist: 2026 May Mark the Peak of the AI Boom

White House Senior Cybersecurity Official Sean Kaincross Resigns
Michael Burry Says He Tried to Warn You About Nvidia, CoreWeave and Nebius. Here's What the 'Big Short' Investor Saw
Ledger CTO Charles Guillemet to Depart by End of 2026

Null Completes $1.7 Million Pre-Seed Funding Round Led by cyber•Fund and Nethermind

Switzerland's First Bitcoin ETF Launches Soon, BIT Hosts Digital Asset Night

The Biggest Investing Lesson I Learned From My First Bear Market

Renowned Crypto Marketing Expert: 5 Major Shifts in Marketing by 2027

BTCPay Server Releases Emergency Update to Fix 5 Nginx Vulnerabilities

Tangem executive sees stablecoin growth in 2027, doubts altcoin season

Is Micron Next to Announce a Stock Split?

IonQ Stock Plunged 48% in Six Months. Is It a Bargain Buy?

Prediction: $200 a Month Invested in SpaceX Could Be Worth This Much by 2035

Where Will Nvidia Stock Be in 3 Years?

Institution: The Financing Situation for AI Computing Power Construction Next Year Becomes Increasingly Abnormal

FTX 'Old Team' Secures US Futures License, 24/7 Trading on the Horizon

A Super Empire on a Fragile Foundation: How Jensen Huang Has Controlled NVIDIA for 33 Years
US Deploys Third Aircraft Carrier to the Middle East as Iran Intensifies Threats Amid Tanker Attack in the Strait of Hormuz

Huya's Q3 2026 Financial Report: Operating Profit Turns Positive for the First Time in Nearly Four Years, Live Streaming and Game-Related Services Continue to Improve Efficiency
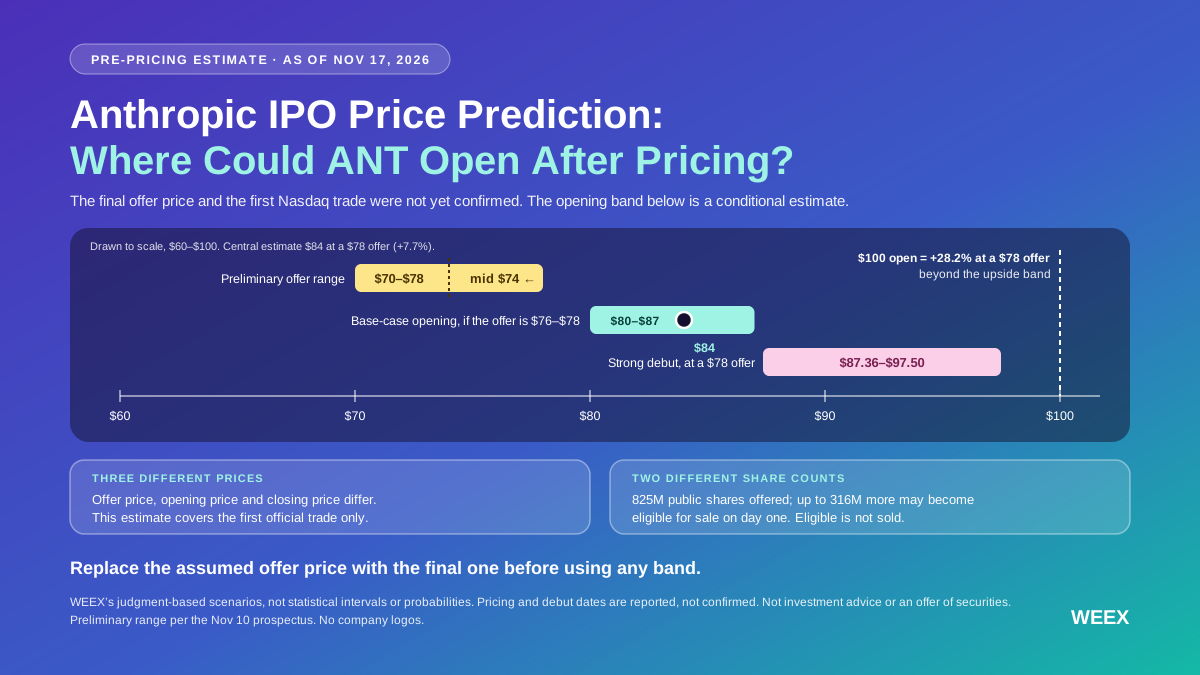
Anthropic IPO Price Prediction: Where Could ANT Open After Pricing?
Anthropic IPO price prediction: See ANT’s $80–$87 base-case opening range, how the final offer price changes it, and what could push shares above $90.

Solana Foundation Requests Node Operators to Address Linux Kernel Vulnerability NoisyTCP

These 3 Dividend Stocks Have Crushed the Market This Year. Here’s Why They Are Still Buys
Nike's Turnaround Is Taking Longer Than Expected. These 3 Stocks May Be Better Buys.
TRON to overtake JD.com? Justin Sun points to 500-person team
CrowdStrike's Acquisition of Zscaler Could Become One of the Largest Deals in Cybersecurity Industry
Walsh Wants Fed Officials to Speak Less, but Their Remarks Have Increased
Would Warren Buffett Buy Anthropic? This Is the One Question He'd Have
NVIDIA Stock Price Falls 40% from Highs, Still Hope Remains
Why Bending Spoons May Choose to Issue Convertible Bonds Next
Moderna vs. BioNTech: Why Only 1 Is a Buy Heading Into 2027
Latest articles




Latest coin listings on WEEX


