
Nvidia Stock Is Down About a Third From Its October Peak. Here's My Estimate for 2030.

 Prefer us on Google


Shares of Nvidia (NVDA -2.01%) ended Oct. 6 at $239.24, a record close. As I write this, they trade near $159, about a third lower.
Some of the fall came this past week. Shares slid 4% on Nov. 12, when Nvidia's board announced Jensen Huang's resignation as CEO. Colette Kress, the company's CFO, is filling in as interim CEO while the board looks for a permanent one.
But the business is growing faster than it was a year ago. And management has already given a rough outlook for its next fiscal year.
With Nvidia's own outlook and some cautious assumptions beyond it, I estimate the stock could trade near $240 at the end of 2030 -- close to where it peaked in October. That'd be about 50% over today's price, or a return of around 10% a year. (This estimate comes before Nvidia's fiscal third-quarter results, due Tuesday, Nov. 17.)
Image source: Nvidia.
Still accelerating
Showing how strong demand remains, Nvidia's revenue growth has sped up for four straight quarters. Sales climbed 62% year over year in fiscal 2026's third quarter, then 73% and 85%. And in the fiscal second quarter of 2027 (the three months ended July 26, 2026), revenue more than doubled, up 106% to $96.2 billion.
Nvidia's fiscal Q3 forecast of $108 billion would put sales for the first nine months of the year around $286 billion. This alone is well over the $215.9 billion Nvidia took in for all of fiscal 2026.
If fourth-quarter sales simply matched that $108 billion, fiscal 2027 revenue would total around $394 billion, up 82%.
On the August earnings call, Kress said management's preliminary expectation is for fiscal 2028 revenue to climb about 70%. That year ends in January 2028. She added that customers' forecasts suggest even faster growth, so the 70% shows what Nvidia can supply, not what buyers want.
Applied to my fiscal 2027 number, that means around $670 billion in revenue.
But earnings likely won't keep up. Memory costs have risen, and Kress expects gross margin to drop to a low of 71% to 72% in the fiscal fourth quarter, down from 75% in fiscal Q2.
My estimate assumes a big slowdown
After fiscal 2028, I've assumed Nvidia's revenue grows just 5% a year, mainly because of what Kress said about supply.
"[W]e expect supply to remain a bottleneck at least through the end of fiscal year 2028," she said.
When chip supply catches up to orders, Nvidia might lose some of its power to set prices. And growing 5% a year from there brings revenue to around $775 billion in fiscal 2031, which ends in January 2031 and closely matches calendar 2030.
Also, Nvidia kept about 56% of its fiscal Q2 revenue as non-GAAP (adjusted) net income. I used 45% for fiscal 2031, a big step down that allows for lower prices and stiffer competition. This comes out to about $349 billion in profit.
Buybacks help, though slowly. Nvidia's diluted share count shrank about 1% over the last year to roughly 24.3 billion, even with $20 billion in repurchases in fiscal Q2 alone. Keeping this pace puts me at about 23.3 billion shares, or earnings per share near $15.
The CEO search might hurt the valuation
Now, the stock costs around 20 times earnings, which is arguably cheap for a business whose sales just doubled. But my estimate has Nvidia growing in single digits by 2030, so I assumed investors pay less: 16 times earnings. At $15 a share, the stock would be worth around $240. Also, the quarterly dividend of $0.25 a share adds a little under 1% a year.
Of course, the biggest risk to this number is the price-to-earnings multiple investors are willing to pay, and the leadership change matters here. The board said it'll consider internal and external candidates for the permanent job. Until it names one, investors could hesitate to pay up for Nvidia's profits.
At 12 times earnings, the same $15 comes to about $180 -- only around 3% a year from here.
Is around 10% a year enough to make the stock worth buying? I think so. Climbing back to $240 doesn't require Nvidia to keep growing fast past next year. It mainly requires the 70% outlook to hold up and investors to pay a normal price for the earnings that follow.
I'd consider buying stock near $159, but I'd keep my position small as the CEO search plays out. Of course, it's just an estimate.
-- Price
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like

'Tokenization Is Not the Finish Line': Jupiter to Let Users Borrow Against Bullish Shares

'Nobody Knows Who's in Charge': Boris Johnson Stands by Bitcoin Skepticism at Breakpoint

Mazama Energy Finds New Solution to the Biggest Challenge in Geothermal Drilling

Have Semiconductors Bottomed? Here's How the Current Chip Stock Plunge Compares With Past Bear Markets.

Is Apple Losing Its Memory?

Rising Transportation Costs Make Large Holiday Purchases More Difficult

Zhao Changpeng Lists Six Possible Reasons for Bitcoin's Decline: Anthropic IPO and ETF Redemptions, Security Incidents, Regulatory Uncertainty, and More

J.P. Morgan's Forecast for 2027: Inflation Around 2% and Increased Pressure on the Dollar

The Amber Controversy: Diverging Paths with Wintermute
First Financial Report After Jensen Huang's Departure: Colette Kress Faces Core Questions

Dreamteam Completes $53 Million Financing to Expand AI CRM Business

Stellar Bell Vote on November 23: What It Means for XLM Holders

Solana Breakpoint attendees warned of robberies after reported wallet theft

Federal Reserve Governor Barr Warns AI Agents May Exacerbate Bank Runs
Trezor found implants in reseller wallets. What protects the buyer?

The Vast Used Car Market: CarMax and Carvana Clash Over Americans' Car Buying Methods
Trump and Xi Jinping to Meet in Shenzhen, Focusing on Chip Regulation and AI Security

Why is the only spot Bitcoin ETF in continental Europe acquired by an Asian group, BIT?

The Application is Landing, Wealth is Evaporating: Analyzing the Painful Roots of the Crypto Industry through Three Financial Statements

A Look at Traditional Banks Entering Web3: Who Made Money and Who Lost?

IMF President Warns Global Economy is 'Standing on One Leg': AI Circular Financing Reaches $1 Trillion

Tesla Autopilot Team Veterans Found Simulation Startup Valued at $1 Billion

Ministry of Industry and Information Technology to Interview Automotive Companies with Large Accounts Payable
Twenty One Capital’s $1.09 Billion Profit Is Mostly a Bitcoin Accounting Story
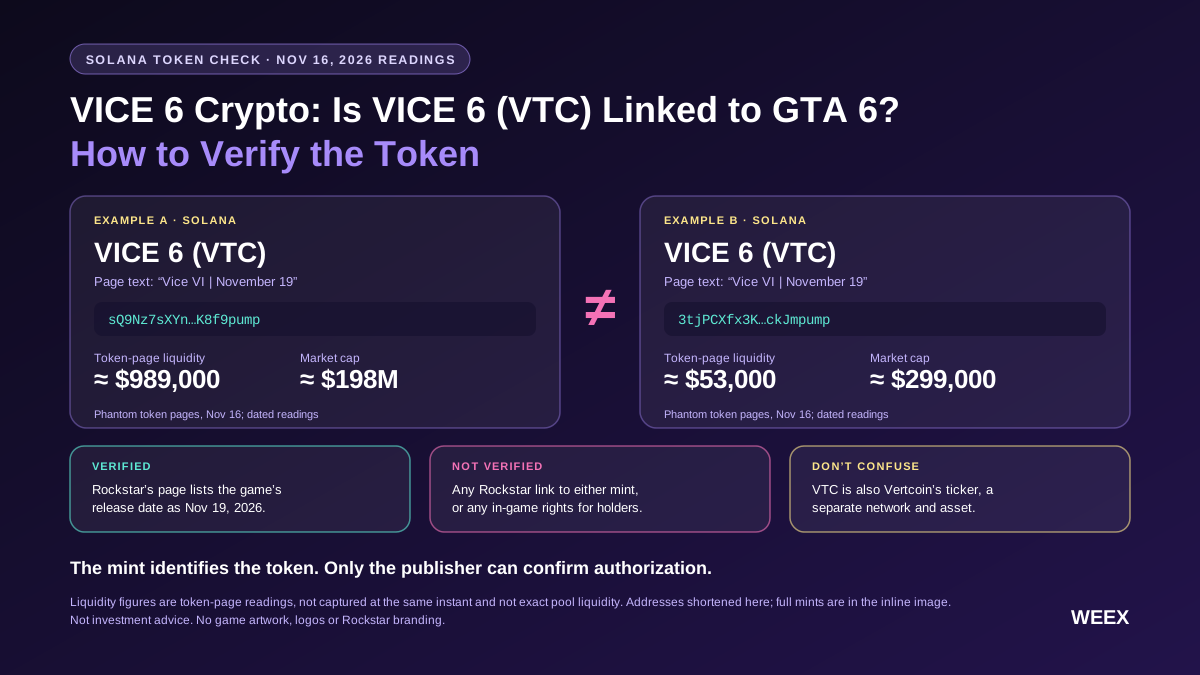
VICE 6 Crypto: Is VICE 6 (VTC) Linked to GTA 6? How to Verify the Token
Is VICE 6 crypto linked to GTA 6? Compare two Solana tokens using VTC, verify their mint and pool addresses, and see what Rockstar has confirmed.

Enterprise Blockchain: Why It's Time to Return?

DTCC Plans to Introduce Tokenized Securities and Bonds on Solana by 2027—Expanding Under Wallet Restrictions

Cardano holders reject 22M ADA treasury bid to buy physical copper

What Licenses Are Needed for Crypto Payments in Hong Kong?
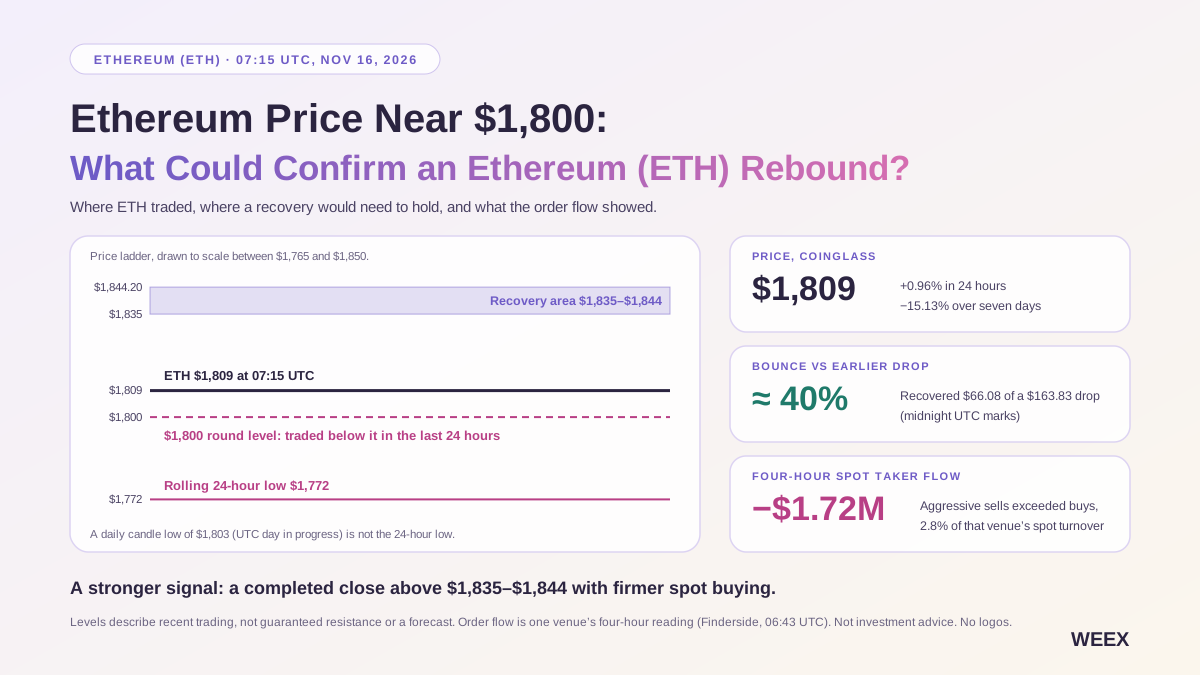
Ethereum Price Near $1,800: What Could Confirm an Ethereum (ETH) Rebound?
Ethereum traded near $1,800 on November 16. See what four-hour spot order flow, futures positioning, and Friday’s ETF flows say about an ETH rebound.
'Tokenization Is Not the Finish Line': Jupiter to Let Users Borrow Against Bullish Shares
'Nobody Knows Who's in Charge': Boris Johnson Stands by Bitcoin Skepticism at Breakpoint
Mazama Energy Finds New Solution to the Biggest Challenge in Geothermal Drilling
Have Semiconductors Bottomed? Here's How the Current Chip Stock Plunge Compares With Past Bear Markets.
Is Apple Losing Its Memory?
Rising Transportation Costs Make Large Holiday Purchases More Difficult
Latest articles




Latest coin listings on WEEX


