
Is CoreWeave Stock a Buy After Its Latest Earnings?

 Prefer us on Google




CoreWeave (CRWV -6.13%) just delivered another impressive quarter. Revenue surged 168% year over year to $3.7 billion, its customer backlog reached $132.5 billion, and management raised its full-year guidance. Yet the company still reported a net loss of $709 million.
For investors, this creates an interesting dilemma. CoreWeave is becoming an increasingly important player in the AI infrastructure market, but its business requires enormous amounts of capital to grow.
I'd consider CoreWeave a speculative buying opportunity after its recent sell-off, but I wouldn't make it a large position in the portfolio just yet. Here are three things investors should consider.
Image source: Getty Images.
The demand is real, and CoreWeave is executing
The strongest part of CoreWeave's latest earnings is its revenue growth.
Quarterly revenue reached $3.7 billion, up from $1.37 billion a year earlier. More importantly, revenue increased approximately 42% sequentially from the previous quarter. Its backlog also expanded to $132.5 billion, up by 138% year over year.
These figures suggest demand for specialized AI computing infrastructure remains strong. CoreWeave is not simply benefiting from enthusiasm surrounding AI. It is winning customers and bringing infrastructure online to serve them.
Management also raised its 2026 revenue guidance to between $13 billion and $13.3 billion. This strengthens the long-term investment case. As AI models become more sophisticated and businesses deploy more AI applications, demand for computing capacity could remain substantial.
However, investors should remember that a large backlog represents future business, not guaranteed profits. CoreWeave still needs to build the infrastructure and deliver computing services before it recognizes much of that revenue.
The biggest challenge is turning growth into profits
CoreWeave generated $2.3 billion in adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA) during the quarter, an impressive 169% increase year over year. But its generally accepted accounting principles (GAAP) operating income was only $207 million. Net interest expense reached $846 million, contributing to a quarterly net loss of $709 million.
Why the difference?
CoreWeave must invest heavily in GPUs, data centers, and electricity to serve its customers. These assets are expensive and lose value over time. The company also borrows substantial amounts to finance its expansion.
This creates a difficult economic equation. CoreWeave needs to keep investing to capture demand, but those investments also generate depreciation and financing costs, creating future funding requirements.
The good news is that management raised its adjusted operating income guidance to between $1.275 billion and $1.375 billion. It also expects to achieve positive adjusted net income in the first half of 2028.
These are encouraging developments, but investors should focus on execution rather than projections. I'd particularly watch whether operating earnings grow faster than interest expenses and whether the company gradually narrows the gap between operating cash flow and capital expenditure.
Until then, impressive revenue growth alone isn't enough to establish that CoreWeave is an attractive investment.
Is the stock cheap enough to justify the risk?
Following its recent sell-off, CoreWeave's valuation has become more interesting. As of this writing, the stock has a market capitalization of around $27 billion. With an expected 2026 revenue of $13 billion to $13.3 billion, the stock trades at roughly 2 times sales.
That might look inexpensive for a company growing revenue at 168%. However, CoreWeave also carries substantial debt. Including its debt and cash position, its enterprise value will be much higher. For perspective, CoreWeave's financial obligations -- debt plus lease obligations -- stand at about $67 billion. This is a more meaningful comparison for a capital-intensive business.
The opportunity is that CoreWeave could become a major AI infrastructure provider if it continues winning customers and improves its operating economics. The risk is that competition from Amazon , Microsoft , and Alphabet intensifies, computing prices decline, and financing costs remain elevated.
I'd therefore avoid treating the recent share-price decline as an automatic buying opportunity. It's definitely cheaper than a few months ago, but it's not a no-brainer.
-- Price
What does it mean for investors?
CoreWeave's latest results strengthen its position as an important AI infrastructure provider. Revenue is growing rapidly, its backlog is expanding, and management is raising its expectations. But the company still has to prove that it can turn its enormous infrastructure investments into sustainable profits.
For investors comfortable with significant volatility, a small initial position could make sense. More conservative investors may prefer to wait for clearer evidence of improving profitability and cash generation before making their next move.
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like

'Tokenization Is Not the Finish Line': Jupiter to Let Users Borrow Against Bullish Shares

'Nobody Knows Who's in Charge': Boris Johnson Stands by Bitcoin Skepticism at Breakpoint

Mazama Energy Finds New Solution to the Biggest Challenge in Geothermal Drilling

Have Semiconductors Bottomed? Here's How the Current Chip Stock Plunge Compares With Past Bear Markets.

Is Apple Losing Its Memory?

Rising Transportation Costs Make Large Holiday Purchases More Difficult

Zhao Changpeng Lists Six Possible Reasons for Bitcoin's Decline: Anthropic IPO and ETF Redemptions, Security Incidents, Regulatory Uncertainty, and More

J.P. Morgan's Forecast for 2027: Inflation Around 2% and Increased Pressure on the Dollar

The Amber Controversy: Diverging Paths with Wintermute
First Financial Report After Jensen Huang's Departure: Colette Kress Faces Core Questions

Dreamteam Completes $53 Million Financing to Expand AI CRM Business

Stellar Bell Vote on November 23: What It Means for XLM Holders

Solana Breakpoint attendees warned of robberies after reported wallet theft

Federal Reserve Governor Barr Warns AI Agents May Exacerbate Bank Runs
Trezor found implants in reseller wallets. What protects the buyer?

The Vast Used Car Market: CarMax and Carvana Clash Over Americans' Car Buying Methods
Trump and Xi Jinping to Meet in Shenzhen, Focusing on Chip Regulation and AI Security

Why is the only spot Bitcoin ETF in continental Europe acquired by an Asian group, BIT?

The Application is Landing, Wealth is Evaporating: Analyzing the Painful Roots of the Crypto Industry through Three Financial Statements

A Look at Traditional Banks Entering Web3: Who Made Money and Who Lost?

IMF President Warns Global Economy is 'Standing on One Leg': AI Circular Financing Reaches $1 Trillion

Tesla Autopilot Team Veterans Found Simulation Startup Valued at $1 Billion

Ministry of Industry and Information Technology to Interview Automotive Companies with Large Accounts Payable
Twenty One Capital’s $1.09 Billion Profit Is Mostly a Bitcoin Accounting Story
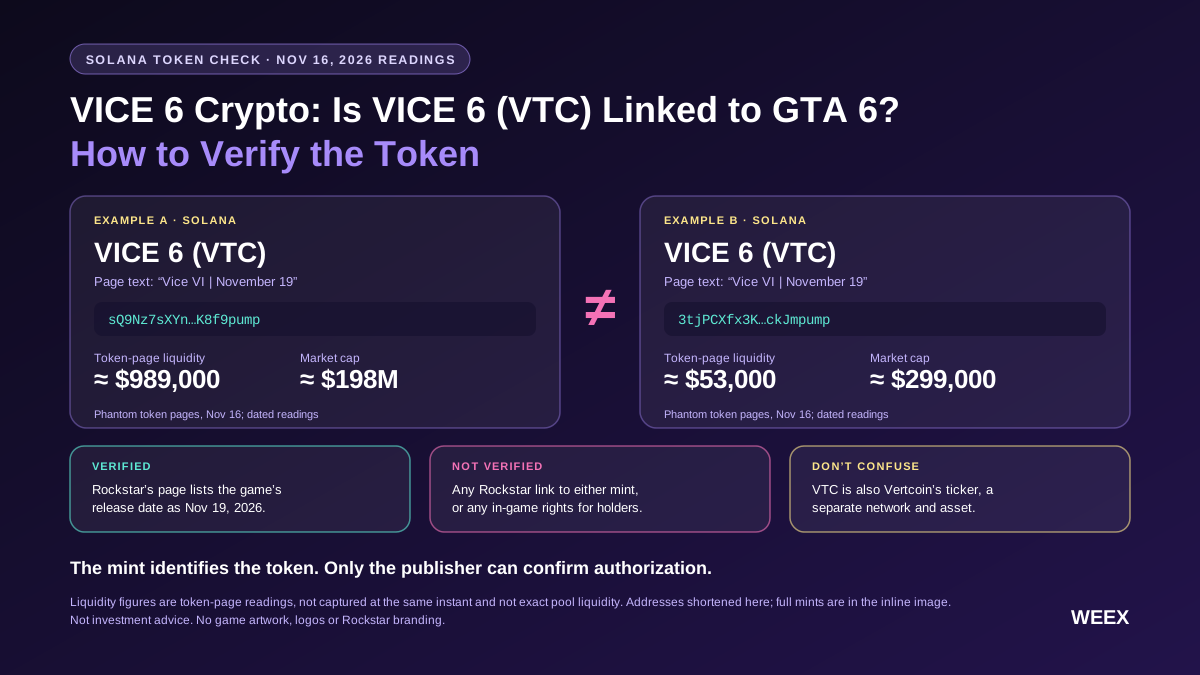
VICE 6 Crypto: Is VICE 6 (VTC) Linked to GTA 6? How to Verify the Token
Is VICE 6 crypto linked to GTA 6? Compare two Solana tokens using VTC, verify their mint and pool addresses, and see what Rockstar has confirmed.

Enterprise Blockchain: Why It's Time to Return?

DTCC Plans to Introduce Tokenized Securities and Bonds on Solana by 2027—Expanding Under Wallet Restrictions

Cardano holders reject 22M ADA treasury bid to buy physical copper

What Licenses Are Needed for Crypto Payments in Hong Kong?
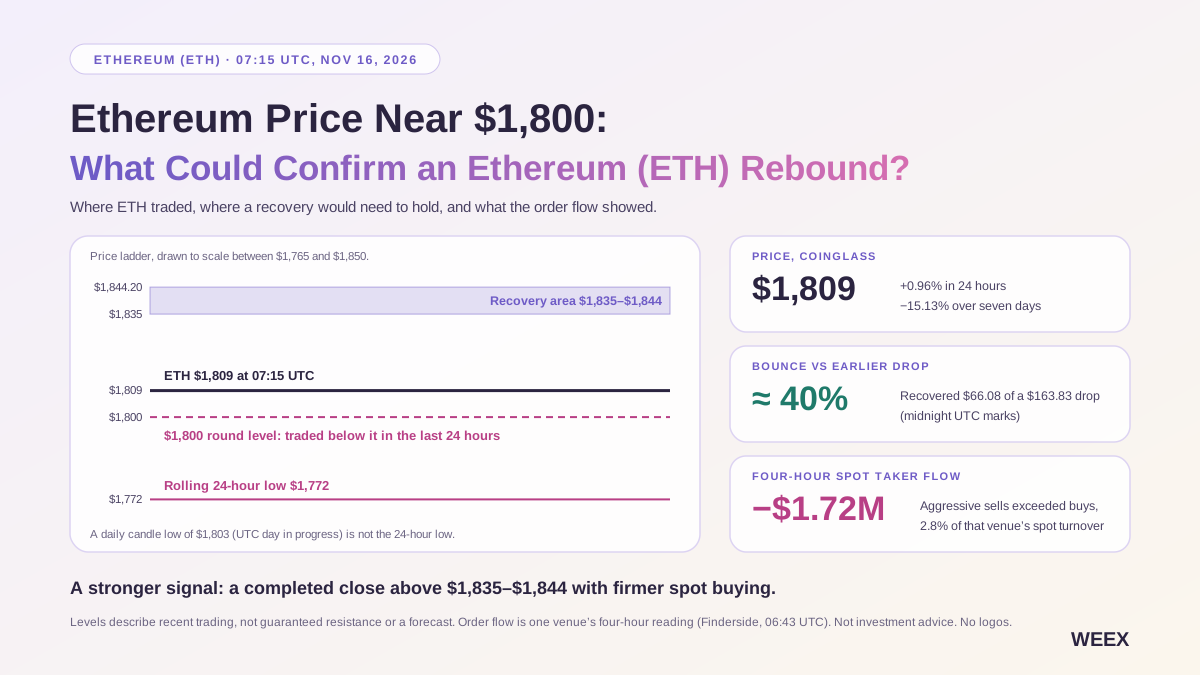
Ethereum Price Near $1,800: What Could Confirm an Ethereum (ETH) Rebound?
Ethereum traded near $1,800 on November 16. See what four-hour spot order flow, futures positioning, and Friday’s ETF flows say about an ETH rebound.
'Tokenization Is Not the Finish Line': Jupiter to Let Users Borrow Against Bullish Shares
'Nobody Knows Who's in Charge': Boris Johnson Stands by Bitcoin Skepticism at Breakpoint
Mazama Energy Finds New Solution to the Biggest Challenge in Geothermal Drilling
Have Semiconductors Bottomed? Here's How the Current Chip Stock Plunge Compares With Past Bear Markets.
Is Apple Losing Its Memory?
Rising Transportation Costs Make Large Holiday Purchases More Difficult
Latest articles


Latest coin listings on WEEX


